A water damage claim goes smoother when you report it early and keep records from the first hour. Texas law also sets deadlines your insurer has to meet.
What a Texas home policy usually covers
The Texas Department of Insurance says most homeowner and renter policies cover sudden and accidental water damage. Its examples are a burst pipe, a toilet overflow, and a broken washer hose. If mold grows on something damaged by a covered water loss, TDI says that mold would be covered too.
What's usually not covered:
- Damage from a slow leak that went on for weeks or months
- Flooding from outside, which needs a separate flood policy
- Mold cleanup and testing beyond the covered damage
- Repairing the pipe or appliance that failed (the water damage it caused is a different matter)
Every policy is different. Read your declarations page and the water damage section, or ask your agent.
The first day: what to do for your claim
- Stop the water and make the house safe.
- Take photos and video of every wet room, the source of the leak, and damaged belongings, before anything is moved or thrown out.
- Report the claim to your insurer and write down the claim number.
- Get drying started. Most policies expect you to take reasonable steps to prevent more damage, and waiting on the adjuster while water sits can hurt your claim.
- Keep the damaged materials or a sample of them, like a piece of carpet and pad, until the adjuster says you can toss them.
- Save every receipt for emergency repairs, equipment, and hotel stays if you have to leave the house.
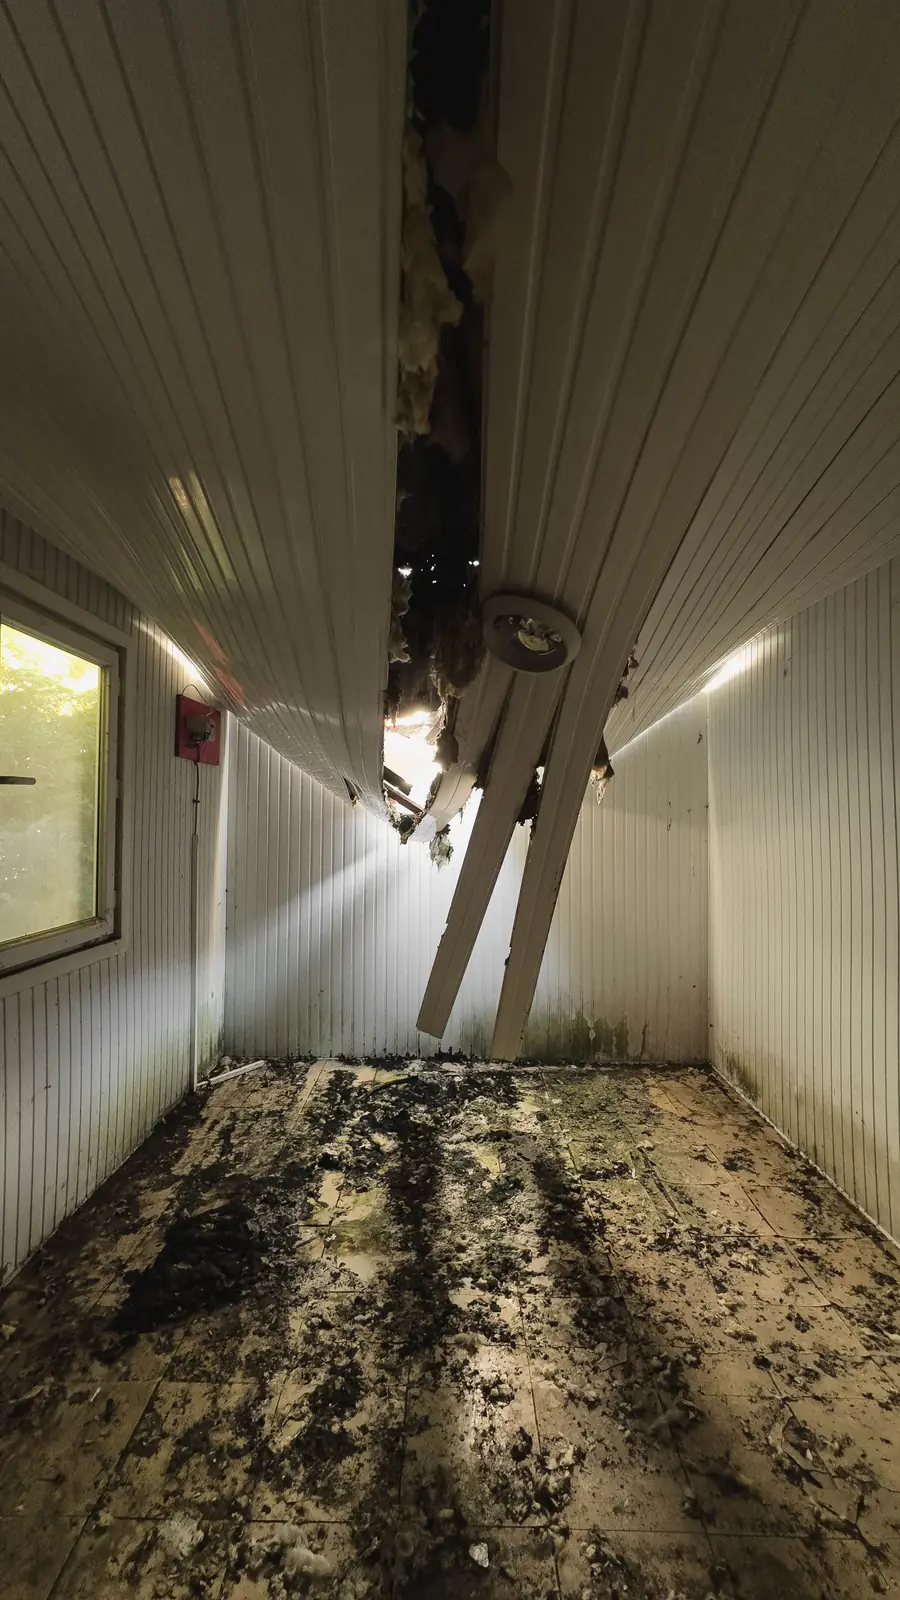
How long your insurer has to respond in Texas
Chapter 542 of the Texas Insurance Code, often called the Prompt Payment of Claims Act, sets these time limits for most insurers:
| Step | Deadline | Section |
|---|---|---|
| Acknowledge the claim, start investigating and ask for what it needs from you | 15 days | 542.055 |
| Accept or reject the claim in writing, after getting everything it asked for | 15 business days | 542.056 |
| If it needs more time, it must tell you why, then decide within | 45 days | 542.056(d) |
| Pay after telling you it will pay | 5 business days | 542.057 |
Surplus lines insurers get longer deadlines. If an insurer that owes a claim doesn't follow these rules, section 542.060 makes it liable for interest at 18 percent a year plus reasonable attorney's fees. Weather related claims under Chapter 542A follow different rules. A lawyer can tell you how any of this applies to your case.
What your adjuster will want from the restoration company
- Photos of the damage before, during and after
- Daily moisture readings for each affected area
- A list of equipment used and how many days it ran
- An itemized estimate for the mitigation and the repairs
Ask for copies of everything. You are entitled to see what is being sent on your behalf.
If the claim is denied or the offer is low
Ask the insurer to explain the denial or the estimate in writing. Under section 542.056, a rejection has to state the reasons. Check whether your policy has an appraisal clause for disagreements about the amount of the loss. You can file a complaint with the Texas Department of Insurance through its website or call TDI at 800-252-3439 with questions. For larger disputes, a licensed public adjuster or an attorney can review the file.
Sources: TDI home insurance guide, Texas Department of Insurance, Texas Insurance Code ch. 542, FloodSmart. Checked October 2026.
Common questions
How long does an insurer have to respond to a water damage claim in Texas?
Under Texas Insurance Code section 542.055, most insurers must acknowledge the claim, start investigating and request the information they need within 15 days of getting notice. After receiving everything they asked for, they generally have 15 business days to accept or reject the claim in writing.
Should I wait for the adjuster before starting cleanup?
No. Take thorough photos and video, report the claim, and then start drying. Most policies expect you to prevent further damage, and waiting while water sits usually makes the damage and the claim bigger.
Is mold covered?
TDI says mold that grows on something damaged by a covered water loss would be covered, but most home policies don't include mold cleanup and testing beyond that. Mold from a flood isn't covered without flood insurance.